EstateFlow Institutional Deal Memorandum
Confidential UK Buy-to-Let Property Analysis • Generated on 04/10/2026
Properties listed under £100,000 boasting 33.05% gross yields frequently require substantial capital expenditure (£15,000 to £30,000+) in structural repairs, heating modernization, and EPC C energy efficiency retrofits to become lettable. Compare the raw asking metrics against all-in underwriting below.
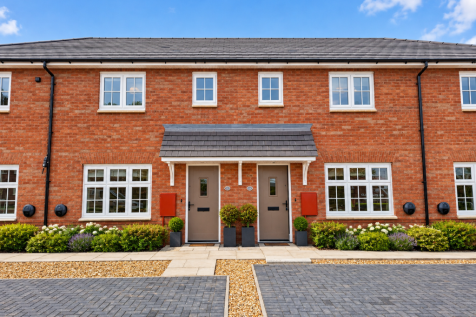
Wrexham Road Chester, CH4
BTL Capital
First Home (95%)
FTB RouteOperating Cashflow
Bank Stress Test (ICR)
True All-In Financial Underwriting
Real-world stress testing accounting for cosmetic refurbishment, structural wear, 10% contingency, and proposed 2028–2030 MEES EPC C compliance.
Itemized CapEx Allocation
Includes loft insulation top-up, smart controls/TRVs, heating commissioning, and localized cosmetic upgrades.
BRRR Refinance & Equity Model (25% Uplift)
Estimated equity uplift of £24,313 upon completion of works. Refinance subject to 6-month ownership rule and surveyor valuation.
Freehold
SPV vs. Personal Name
Holding this property inside a Limited Company (SPV) saves approx. £4,627/yr in tax because 100% of mortgage interest is tax-deductible against 19% Corporation Tax.
Multi-Let Potential
No citywide Article 4 restriction detected. Standard Permitted Development rights (Class L) may apply, subject to local council licensing rules.
Institutional Investor Notice & 2026 Tax Rules:
Calculations account for the Autumn Budget residential second-home Stamp Duty surcharge (5% on the initial £250,000 bracket). Mortgage figures are simulated based on standard 75% LTV buy-to-let interest-only products at 5.2%. Independent professional conveyancing and financial advice should always be obtained prior to exchange of contracts.Need a 20% deposit Buy-to-Let mortgage, equity release remortgage, or 28-day auction bridging facility?